Introduction
Deciding where to put your hard-earned money can feel overwhelming. When you step into the world of investing, two terms appear almost immediately: stocks and mutual funds.
Many beginners treat these words as interchangeable options in a shopping aisle, but they represent entirely different ways of growing wealth. Choosing incorrectly can lead to sleepless nights worrying about market crashes or missed opportunities for growth.
This article cuts through the financial jargon to explain how stocks and mutual funds differ. You will learn how each one works, the hidden risks involved, and a simple framework to help you decide which path fits your financial situation.
What Is a Stock?
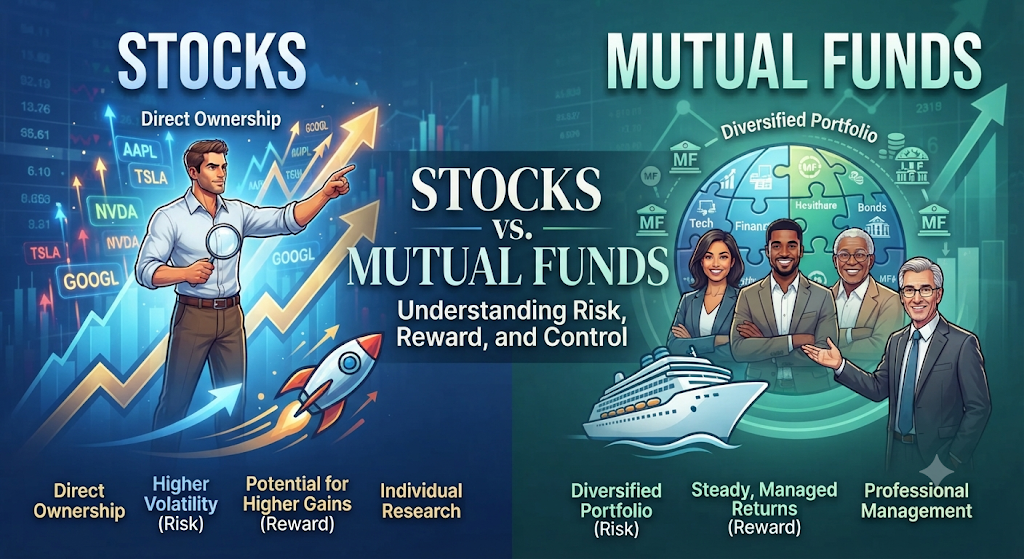
A stock (also called equity or a share) is a fractional ownership certificate in a publicly traded corporation.
Why It Matters
When you purchase a share of a company like Apple or Microsoft, you become a part-owner of that business. Your fortunes are directly tied to that specific company’s performance, management decisions, and industry trends.
How It Works
Companies issue stocks to raise capital for business expansion, research, or paying off debt. Investors buy these shares through a stockbroker or trading platform.
- Capital Appreciation: If the company grows and becomes more profitable, other investors will pay more to buy your share, raising its market value.
- Dividends: Some established companies distribute a portion of their quarterly profits directly to shareholders as cash payments called dividends.
Example
Imagine you buy 10 shares of a local coffee shop chain for $50 per total share investment. If the chain expands successfully and profits soar, other investors might value those shares at $80 each. You can sell them to lock in a profit. However, if a major health scandal hits the coffee chain, the share price might drop to $20, resulting in a loss if you sell.
What Is a Mutual Fund?
A mutual fund is a professionally managed investment vehicle that pools money from thousands of individual investors to purchase a diversified portfolio of securities.
Why It Matters
Instead of betting everything on a single company, a mutual fund lets you buy a tiny slice of an entire market basket—sometimes containing 100 to 500 different stocks and bonds—with a single transaction.
How It Works
A financial institution hires a fund manager (or uses an automated computer algorithm for index funds) to pick and monitor the assets inside the fund according to a specific strategy.
- Net Asset Value (NAV): The price of a mutual fund is calculated daily based on the total value of all securities inside the fund divided by the number of shares issued to investors.
- Professional Management: Experts handle the research, buying, and selling so you do not have to analyze individual corporate balance sheets.
Example
Suppose you want to invest in the technology sector, but you only have $100. Buying single shares of ten major tech giants would cost thousands of dollars. Instead, you put your $100 into a technology mutual fund. That money combines with millions from other investors, allowing the fund to buy shares in all ten companies simultaneously. Your $100 now gives you fractional ownership across the entire tech portfolio.
Key Differences Between Stocks and Mutual Funds
To understand how stocks and mutual funds differ in practice, it helps to compare them across core operational categories.
| Feature | Stocks | Mutual Funds |
|---|---|---|
| Ownership Structure | Direct ownership in a specific single company. | Indirect ownership in a diversified basket of many assets. |
| Risk Level | Generally higher; concentrated in one business or sector. | Generally lower; buffered by built-in diversification. |
| Time Commitment | High; requires ongoing research and performance tracking. | Low to moderate; managed by professionals or set-and-forget indexes. |
| Cost to Buy | Brokerage commissions or per-share purchase prices. | Expense ratios (annual management fees) and potential entry/exit loads. |
| Control | Complete control over when to buy, hold, or sell specific companies. | No direct control over individual underlying asset trades. |
Why Mutual Funds Provide Built-In Protection
The concept of diversification is the primary reason many investors choose mutual funds over individual stocks.
What Diversification Means
Diversification simply means spreading your money across different types of investments so that a failure in one area does not ruin your entire portfolio.
Why It Matters
If you invest all your savings into a single airline stock and that airline faces bankruptcy, your investment can be wiped out. In a mutual fund that holds 200 different stocks, if one company goes bankrupt, its impact is cushioned by the 199 other companies in the fund that may be thriving.
Costs and Expenses to Watch Out For
Investing is never free, and the fee structures for stocks and mutual funds vary significantly.
- Stock Transaction Fees: When buying individual stocks, you might pay a small trading commission or platform fee per transaction, though many modern online brokers offer commission-free trading.
- Mutual Fund Expense Ratios: Mutual funds charge an annual operational fee known as an expense ratio. This is a small percentage (ranging from 0.05% to over 1.5% annually) deducted automatically from the fund’s assets to cover management salaries, administrative costs, and research.
Why It Matters
High expense ratios can quietly eat away at your long-term returns. Over a 20-year period, paying an extra 1% in annual fees can cost you thousands of dollars in compounding growth.
Common Mistakes Beginners Make
Entering the market without a clear plan often leads to costly errors. Watch out for these common missteps:
- Chasing Past Performance:
- What people do: Buying a mutual fund or stock just because it had an amazing return last year.
- Why it causes problems: Financial markets change constantly; historical success does not guarantee future results.
- What to do instead: Focus on long-term consistency, low fees, and alignment with your personal financial goals.
- Putting All Eggs in One Basket:
- What people do: Buying five different tech stocks and thinking they are fully diversified.
- Why it causes problems: If the entire tech sector drops, all five stocks fall together.
- What to do instead: Spread investments across different industries (healthcare, finance, technology, consumer goods).
- Panic Selling During Market Dips:
- What people do: Selling everything at a loss the moment stock prices or fund NAVs drop.
- Why it causes problems: You lock in your losses and miss the subsequent market recovery.
- What to do instead: Maintain a long-term perspective and view temporary market drops as normal economic cycles.
Decision-Making Framework: Which Should You Choose?
Use this step-by-step checklist to determine whether stocks, mutual funds, or a combination of both fit your investing style.
- Step 1: Evaluate Your Available Time. Do you have hours each week to read financial statements, analyze quarterly earnings reports, and track market news? If yes, stocks may suit you. If no, mutual funds are a better fit.
- Step 2: Assess Your Risk Tolerance. Can you stomach watching a single company’s stock drop 30% in a week due to bad news? If that causes anxiety, mutual funds offer a smoother, less volatile ride.
- Step 3: Check Your Starting Capital. If you have a small amount of money to invest each month (e.g., $50), buying shares of high-priced individual companies is difficult. Mutual funds let you invest small amounts into diversified portfolios instantly.
- Step 4: Define Your Investment Horizon. Are you investing for retirement decades away, or trying to make short-term gains? Long-term wealth building often benefits greatly from the steady compounding of diversified mutual funds or index funds.
Checklist for New Investors
Before placing your first trade or buying your first fund, verify these core points:
- I have defined my financial goals and know how long I plan to keep my money invested.
- I understand the fees associated with my chosen brokerage account or mutual fund.
- I have built an emergency fund for unexpected expenses so I won’t be forced to sell investments during a market downturn.
- My portfolio is spread across different assets to protect against single-industry crashes.
Key Terms
- Asset Allocation: The strategy of dividing your investments among different categories, such as stocks, bonds, and cash.
- Bear Market: A market condition where stock prices fall broadly by 20% or more over a sustained period.
- Bull Market: A market condition characterized by rising stock prices and widespread investor optimism.
- Dividend: A portion of a company’s earnings paid out regularly to its shareholders.
- Expense Ratio: The annual fee charged by mutual funds to cover management and operating costs.
- Index Fund: A type of mutual fund designed to track the performance of a specific market index, like the S&P 500.
- Liquidity: How quickly and easily an investment can be converted into cash without affecting its market price.
- Portfolio: A collection of financial investments like stocks, bonds, and mutual funds held by an investor.
- Volatility: The speed and severity with which an investment’s price moves up and down over time.
Frequently Asked Questions
Can I lose all my money in a mutual fund?
While it is possible for the value of a mutual fund to drop significantly during severe economic downturns, losing 100% of your money in a broad market mutual fund is extremely rare. Because mutual funds hold dozens or hundreds of different assets, the complete failure of one company will not destroy the entire fund. In contrast, individual stocks carry a higher risk of total loss if the specific company goes bankrupt.
Which option offers higher returns?
Neither option guarantees higher returns. Individual stocks have the potential for massive gains if you pick a company that grows exponentially, but they also carry a much higher risk of sharp losses. Mutual funds typically offer more moderate, stable long-term growth by smoothing out the highs and lows of the broader market.
Do I need a lot of money to start investing in mutual funds?
No. Many mutual funds and index funds allow you to start investing with modest amounts of money, sometimes as little as $25 or $50 through systematic investment plans. This makes mutual funds much more accessible for beginners than buying individual high-value stocks.
Are mutual funds safer than stocks?
Generally, yes. Safety in investing usually refers to risk reduction through diversification. Because a mutual fund spreads your money across many different companies and industries, a stumble by one business has a minimal impact on your overall investment. Stocks lack this built-in buffer.
How are mutual fund returns taxed?
When you sell mutual fund shares for a profit, or when the fund manager sells underlying stocks inside the fund for a profit (resulting in capital gains distributions), you may owe taxes. The specific tax rules depend on your local tax laws and whether you hold the fund in a tax-advantaged retirement account.
Can I sell my mutual fund shares at any time?
Most open-ended mutual funds allow you to sell your shares on any business day. Once the market closes for the day, your shares are bought back at that day’s final Net Asset Value (NAV), and the cash typically settles in your account within a few business days.
Conclusion
Choosing between stocks and mutual funds comes down to your personal comfort with risk, time, and control.
If you enjoy analyzing businesses, have time to monitor the markets, and want direct ownership of specific companies, individual stocks offer a hands-on approach. If you prefer a simpler, hands-off strategy built on diversification and professional oversight, mutual funds provide a reliable path to long-term wealth building.
Take your time, assess your financial goals, and choose the path that aligns with your comfort level.